
Estate planning secures hard-earned assets for your loved ones without unnecessary legal stress. Middle-class families…
Build Wealth in Your 60s with 500k
Is It Too Late to Build Wealth at My Early 60s with a Minimum of Half a Million?
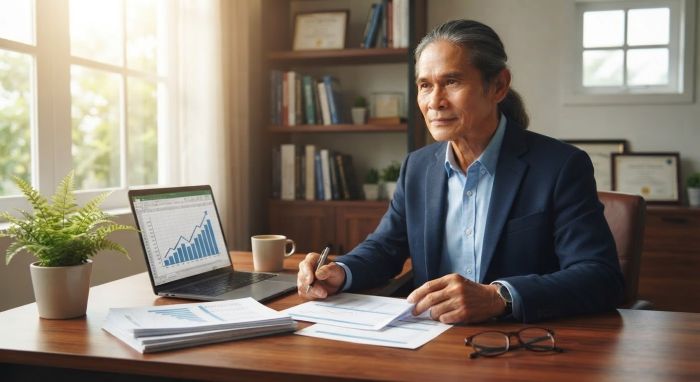 Entering your early 60s with five hundred thousand dollars provides a powerful financial foundation to build wealth effectively. Many people assume that building net worth belongs exclusively to younger generations. However, modern medical advances extend active life expectancy well into your late 80s or 90s. You possess a potential investment horizon spanning two to three decades right now. Starting with half a million dollars gives you significant capital leverage for future growth. Wise asset allocation transforms this initial lump sum into a growing source of lifelong income. Your age brings valuable life experience, emotional discipline, and clear financial priorities.
Shifting Your Financial Mindset for Growth
Traditional financial advice often instructs sexagenarians to move capital entirely into low-yielding cash accounts. Taking zero risk actually destroys purchasing power through relentless annual inflation forces over time. Instead, balance capital preservation strategies with calculated growth opportunities across diverse asset classes. A half-million-dollar portfolio provides sufficient fuel to generate meaningful investment returns continuously.
You must view your early 60s as a vibrant growth phase rather than an immediate financial shutdown. Treat your capital as an active working engine that generates new revenue streams daily. Refusing to settle for meager savings yields keeps your money compounding productively for years. Growth remains entirely achievable when you deploy structured, sensible investment parameters.
Harnessing the Power of Dividend Growth Stocks
Dividend-paying stocks offer an exceptional combination of steady current income and long-term capital appreciation. Selecting established companies with strong balance sheets ensures reliable quarterly payout distributions over time. Reinvesting these cash dividends back into the portfolio accelerates total compound growth exponentially during early retirement years.
Furthermore, high-quality dividend growth companies regularly raise their cash payouts faster than general inflation rates. This expanding income stream shields your living standard from rising consumer costs automatically. You avoid selling off foundational shares to fund living expenses when dividends cover your basic financial needs. Consequently, your underlying share count remains intact, capturing future market gains seamlessly.
Optimizing Real Estate for Passive Cash Flow
Real estate investments provide physical asset security, tax benefits, and steady monthly rental income. Allocating a portion of your half-million dollars into real estate diversifies your overall wealth strategy effectively. You can purchase residential rental properties outright or invest in commercial Real Estate Investment Trusts.
Rental properties generate consistent monthly cash flows while underlying real estate values appreciate over long holding periods. Tax deductions for property depreciation offset a significant portion of your taxable rental income legally. Alternatively, real estate investment trusts offer liquidity and high yield without landlord management responsibilities. Adding real estate assets stabilizes your total portfolio against broad stock market volatility.
Preserving Capital with Fixed-Income Allocation
Growth strategies require a solid foundation of reliable, low-risk fixed-income assets for overall portfolio stability. Treasury bonds, corporate bonds, and high-yield certificates of deposit protect essential core liquidity. Securing predictable yield payouts ensures you never panic during sudden equity market downturns.
A well-structured bond ladder generates predictable cash distributions arriving at regular intervals throughout the year. Maturing bonds provide ready cash to fund immediate living expenses or buy discounted equities during market dips. Balancing equities with fixed-income instruments optimizes risk-adjusted returns while safeguarding your principal capital. This stability grants essential peace of mind, allowing long-term growth assets time to compound smoothly.
Maximizing Tax-Efficient Investment Accounts
Tax efficiency plays a critical role in preserving total investment returns as your assets expand rapidly. Utilize traditional Individual Retirement Accounts, Roth IRAs, and health savings accounts to minimize tax burdens legally. Converting portions of traditional IRA funds into Roth accounts during lower-income years creates tax-free future withdrawals.
Tax-free growth inside a Roth IRA allows your half-million dollars to compound completely unimpeded by annual capital gains taxes. Additionally, strategic asset placement places high-yield investments inside tax-deferred accounts while keeping tax-efficient assets in taxable brokerage accounts. Minimizing tax drag keeps significantly more capital working productively inside your growing portfolio. Consulting a qualified tax professional uncovers subtle opportunities to retain hard-earned investment gains.
Utilizing Modern Low-Cost Index Funds
Low-cost index funds provide instant broad-market diversification across thousands of global public enterprises efficiently. Broad market funds capture overall economic expansion while keeping annual management fees exceptionally low. Minimizing expense ratios ensures more of your investment returns remain directly inside your investment account over decades.
Index funds eliminate single-company collapse risks through broad structural diversification across major economic sectors. You capture consistent market returns without spending endless hours analyzing individual financial statements daily. Holding global index funds exposes your capital to booming international markets alongside domestic market gains. This hands-off approach builds lasting wealth while freeing your time for fulfilling retirement lifestyle pursuits.
Creating a Sustainable Withdrawal Strategy
Building wealth in your 60s requires balancing aggressive portfolio compounding with safe, controlled distribution rates. The classic four percent withdrawal rule offers a helpful baseline for planning annual portfolio distributions safely. Adjusting your withdrawal rate based on annual market performance protects your core capital during temporary economic downturns.
Flexibility remains the cornerstone of long-term financial survival throughout your extended retirement years. Withdrawing less during weak market years allows your underlying investments to recover rapidly when markets rebound. Meanwhile, strong market performance permits higher distributions to enjoy special life experiences or fund family legacies. Managing distributions intelligently ensures your initial half-million dollars outlasts your physical lifetime comfortably. You retain absolute control over your financial destiny while continuously expanding your net worth.

Related Posts
This Post Has 0 Comments